BIR EIS e-invoicing compliance before 31 December 2026
Structured JSON invoices, digitally signed and transmitted to the BIR Electronic Invoicing System within three calendar days — built into your ERP rather than bolted on beside it.
The Electronic Invoicing System is the BIR's platform for receiving invoice data directly from taxpayers'
systems. Under Revenue Regulations No. 11-2025 (issued 27 February 2025, effective
14 March 2025) — with the first-group deadline extended by Revenue Regulations No. 26-2025
(issued 5 September 2025) — covered taxpayers must transmit invoice data electronically, not merely produce
a digital-looking document.
The obligation rests on Sections 237 and 237-A of the National Internal Revenue Code, as amended by the
CREATE MORE Act.
The two regulations that define the current deadline
Two issuances set the clock and the scope. The first moved the date; the second split one obligation into two.
RR No. 26-2025 · Issued 5 September 2025
The absolute deadline moved to 31 December 2026
This regulation extended the absolute deadline for mandatory compliance to 31 December 2026. It was granted to give businesses sufficient time to reconfigure their internal accounting processes and software architectures.
RMC No. 98-2026 · Recent clarification
Issuance and transmission are now separate obligations
This circular officially separates the legal obligation of issuing an e-invoice to a customer from the ongoing obligation of transmitting that data live to the BIR backend.
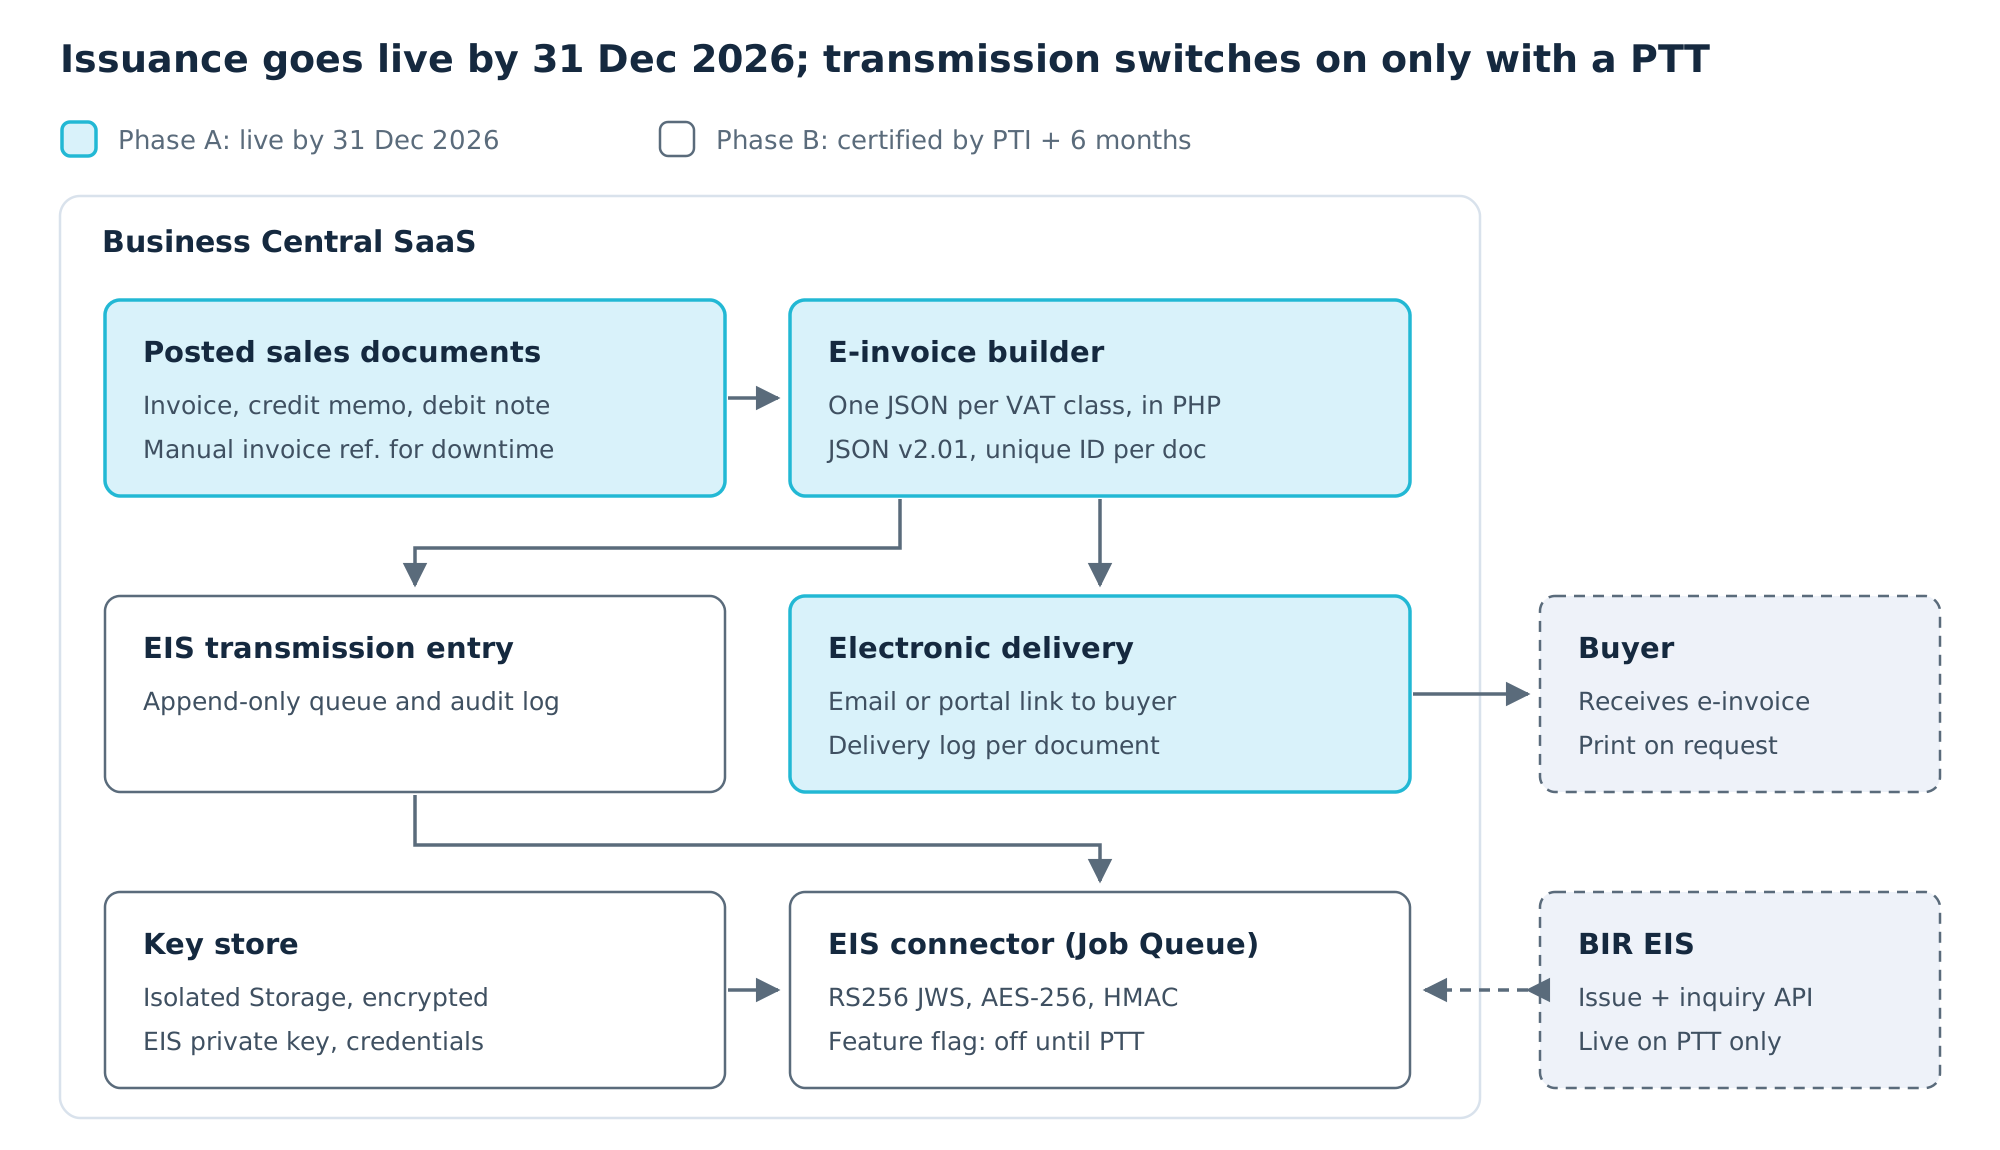
The practical consequence is that the 31 December 2026 date applies to issuance — a compliant e-invoice, correctly structured and delivered to your buyer. Transmission to the BIR backend is gated separately: it begins only once the Bureau grants your Permit to Transmit, with EIS certification due within six months of the Permit to Issue. Build for both, switch on in the order the Bureau allows.
Phase A and Phase B are not two projects. They are one build with a feature flag: the issuance path runs from day one, while the transmission path sits configured, signed and idle until your Permit to Transmit lands.
Issuance goes live by 31 Dec 2026; transmission switches on only with a Permit to Transmit. Shaded blocks are Phase A; outlined blocks are Phase B. Open full size →
Who must comply by 31 December 2026
The first compliance group covers:
Taxpayers registered with the Large Taxpayers Service (LTS)
Taxpayers classified as large under the Ease of Paying Taxes Act — broadly, annual
gross sales above ₱1 billion
E-commerce and internet-based businesses — digital goods, digital services and
platform commerce
Taxpayers using a Computerized Accounting System (CAS), Computerized Books of Accounts (CBA),
or e-invoicing software
Branches are covered as well as head offices. The fourth category is the one most often
missed: if you already run a registered CAS — which many mid-sized Philippine businesses do — you are in the
first group regardless of your revenue. Remaining taxpayer categories, including exporters, point-of-sale
users and registered business enterprises with incentives, follow on dates the BIR has yet to announce.
Not sure which group you fall into? Classification turns on your BIR registration and your
current systems, not on headcount. Send us your situation and we will tell you
plainly — this is a factual question, not a sales one.
The technical requirements
Requirement
Detail
File format
Structured JSON. XML is accepted as an internal format but
not for transmission to the BIR.
Digital signature
Each invoice must be validated with a digital signature before
transmission.
Transmission
System-to-system API connection between your invoicing or
ERP software and the BIR EIS. Manual upload is not the compliance path.
Timing
Invoice data must reach the EIS within three calendar days of the
transaction.
Data elements
A minimum set of roughly 54 fields, including seller and buyer TIN,
timestamped issue date, line-item detail, VAT rate and grand total.
Penalties for non-compliance
Failure to comply with the e-invoicing mandate carries penalties of ₱1,000 to ₱50,000 per
offence under the Tax Code. The larger commercial exposure is operational: if you cannot issue a
compliant invoice, you cannot bill, and collections stop. That risk is why we push clients to cut over with
time for parallel running rather than in the final weeks of December.
How we deliver EIS readiness
Scope confirmation. We establish which compliance group applies to your entity and
each of its branches.
Data readiness. The ~54 required elements are mapped against your master data. This is
where most projects discover missing buyer TINs and inconsistent item descriptions — it is better to find
that in month one than in December.
Generation and signing. Business Central produces the structured JSON payload and
applies the digital signature as part of the posting flow, not as a separate clerical step.
Transmission. System-to-system connection to the EIS, with retry handling and a
transmission log you can evidence during audit.
Parallel run. Live invoices transmitted alongside your existing process until the
acknowledgement rate is clean, then cutover.
EIS and CAS together
These two obligations interlock. Holding a registered CAS puts you in the first EIS group; conversely,
building EIS transmission into a system that is not properly registered creates a documentation gap. We
sequence CAS registration and EIS readiness as one programme inside
the Business Central implementation.
Critical points per Revenue Regulation
Seven Revenue Regulations shape what an e-invoice must contain, who must issue it and by when. The register below gives the status of each; the cards that follow set out the points that matter for planning and audit.
RR No.
Subject
Date / effectivity
Status
8-2022
EIS policies: e-invoices and sales data transmission (TRAIN)
Issued 30 Jun 2022; pilot Jul 2022
In force; supplemented by RR 11-2025
9-2022
Admissibility of electronic sales documents in audit and VAT refunds
Published 1 Jul 2022
In force
7-2024
EOPT invoicing: the invoice replaces the official receipt
Effective 27 Apr 2024
In force; sets the content every e-invoice must carry
11-2024
Amends the RR 7-2024 transitory rules, including CRM, POS and e-invoicing software
13 Jun 2024
In force; transition period has lapsed
11-2025
Primary e-invoicing and electronic sales reporting rules under CREATE MORE
Issued 27 Feb 2025; effective 14 Mar 2025
Primary governing regulation
26-2025
Extends the RR 11-2025 e-invoicing deadline
Dated 5 Sep 2025; published 16 Oct 2025
In force; sets the 31 Dec 2026 deadline
6-2026
Creditable withholding tax shown as a separate line on invoices
Effective 16 Oct 2026
In force; changes the invoice layout
RR No. 8-2022 · EIS foundation under the TRAIN Law
The original EIS rules: certification, enrolment and transmission
Coverage: exporters of goods and services, e-commerce taxpayers, and taxpayers under the Large Taxpayers Service.
Transmission: covered taxpayers other than e-commerce sellers report sales data to the BIR through a Sales Data Transmission System.
System obligations: build the transmission system on the BIR's standard API guidelines, enrol before the first transmission, obtain EIS certification and secure a Permit to Transmit, whatever the arrangement with the software provider.
Data format: sales data, not source documents, is sent through the API in JSON. Source documents include invoices, debit and credit notes and other adjustment documents.
Pilot: began in July 2022 with about 100 selected large taxpayers.
RR No. 9-2022 · Admissibility of electronic sales documents
EIS data becomes audit evidence, and gaps become findings
Audit use: sales and purchase data generated and verified through the EIS is admissible in audit, and printed invoices are not required.
Unreported-sales risk: an invoice the supplier fails to report to the EIS is treated as an unreported sale and may be investigated further.
System access: revenue officers may still access the taxpayer's CAS, POS or CRM to validate transmitted data. Refusal can lead to disallowances, prosecution or revocation of the system permit.
Related change: the five-year validity period on manual and system-generated invoices was removed from 16 July 2022.
RR No. 7-2024, as amended by RR No. 11-2024 · EOPT invoicing
The content baseline every e-invoice must meet
Primary document: the invoice is now the primary evidence of sale for both goods and services; the official receipt is no longer the primary document for services.
Supplementary receipts: official receipts used as supplementary documents must be stamped “This document is not valid for claim of input tax.”
System relabelling: for CRM, POS and e-invoicing software, changing “Official Receipt” to “Invoice” is a minor enhancement and does not need to be reported to the RDO.
Penalty exposure: a VAT-registered seller that issues a VAT invoice missing mandatory information is liable for non-compliance.
RR No. 11-2025 · Primary regulation under CREATE MORE
Who is covered, what counts as an e-invoice, and the tax incentive
Legal basis: implements Sections 237 and 237-A of the Tax Code as amended by CREATE MORE, covering both e-invoice issuance and electronic sales reporting.
Definition: a photo or scan of a paper invoice is not an electronic invoice. Electronic sales reporting means system-to-system transfer of structured invoice data to the BIR, with no manual entry.
First group (issuance mandate): e-commerce and internet sellers, taxpayers under the Large Taxpayers Service, large taxpayers under the EOPT classification, and users of CAS, CBA with accounting records or other invoicing software.
Second group (once the BIR system is ready): exporters, POS users and registered business enterprises availing of incentives, on dates to be set by later regulations.
Branches: where the covered taxpayer or activity is registered to a branch, the head office and every branch are covered.
Micro taxpayers: exempt from the mandate but may adopt e-invoicing voluntarily.
Additional deduction: 100% of the cost of setting up an electronic sales reporting system for micro and small taxpayers; 50% for medium and large taxpayers. Claimable once, in the taxable year the system is completed or final payment is made. Imports connected with the system are tax-exempt.
Penalties: non-compliance is penalised under Sections 264 and 264-A of the Tax Code.
RR No. 26-2025 · Deadline extension
31 December 2026 replaces 14 March 2026
New deadline: the first group must comply with e-invoicing by 31 December 2026, instead of 14 March 2026.
Scope unchanged: the extension does not alter who is covered under RR 11-2025.
Further extensions: the Commissioner may extend the period again if necessary. Plan around the current date, not a possible extension.
Dates on record: the regulation is dated 5 September 2025 and was published on 16 October 2025. Record both in your compliance file.
RR No. 6-2026 · Creditable withholding tax on invoices
A new mandatory line on every invoice, printed or electronic
Requirement: where applicable, the creditable withholding tax amount must appear as a separate item on the invoice.
Lead time: took effect on 16 October 2026, fifteen days after publication on 1 October 2026.
Open points: the transitory rule addresses manual invoices but not CAS or POS invoices, and the BIR has yet to confirm how the line maps to the EIS data schema. Invoice layouts and the e-invoice payload should carry a configurable withholding field now.
Two circulars complete the operating picture: RMC No. 98-2026 (Permit to Issue, EIS certification, downtime and correction rules) and RMC No. 110-2026 (accreditation of electronic invoicing service providers). These are circulars rather than regulations, but the Permit to Issue they require is a precondition for issuing e-invoices on 31 December 2026.
This page summarises publicly available regulatory information for planning purposes. It is not tax
advice. Confirm your specific obligations with your tax adviser or your Revenue District Office.
Questions
Frequently asked questions
Does the 31 December 2026 deadline apply to my business?
It applies if you are registered with the Large Taxpayers Service, classified as a large taxpayer under the Ease of Paying Taxes Act, engaged in e-commerce or internet-based selling, or already using a Computerized Accounting System, computerised books of accounts or e-invoicing software. Branches are covered as well as head offices. Other categories follow on BIR-announced dates.
Is a PDF invoice sent by email enough?
No. The EIS requires structured JSON data, digitally signed, transmitted to the BIR over a system-to-system API connection within three calendar days. A PDF is a human-readable rendering, not the compliance artefact.
How long does EIS readiness take to implement?
For a business already on Business Central, transmission is a configuration and connection exercise measured in weeks. For a business still on spreadsheets or a legacy package, the ERP implementation is the critical path — which is why starting in Q4 is uncomfortably tight.
What are the penalties for missing the deadline?
Penalties of ₱1,000 to ₱50,000 per offence apply under the Tax Code. The operational consequence matters more: an inability to issue compliant invoices interrupts billing and collection.
Do we need a separate e-invoicing vendor on top of our ERP?
Not if the ERP can generate, sign and transmit natively. Adding a separate middleware layer adds a failure point and a second reconciliation. We build transmission into the Business Central posting flow so the invoice and the transmission are one event.
Find out where you stand before Q4
Tell us your BIR registration type and current systems. We will confirm which compliance group applies and what readiness actually requires for your setup.